
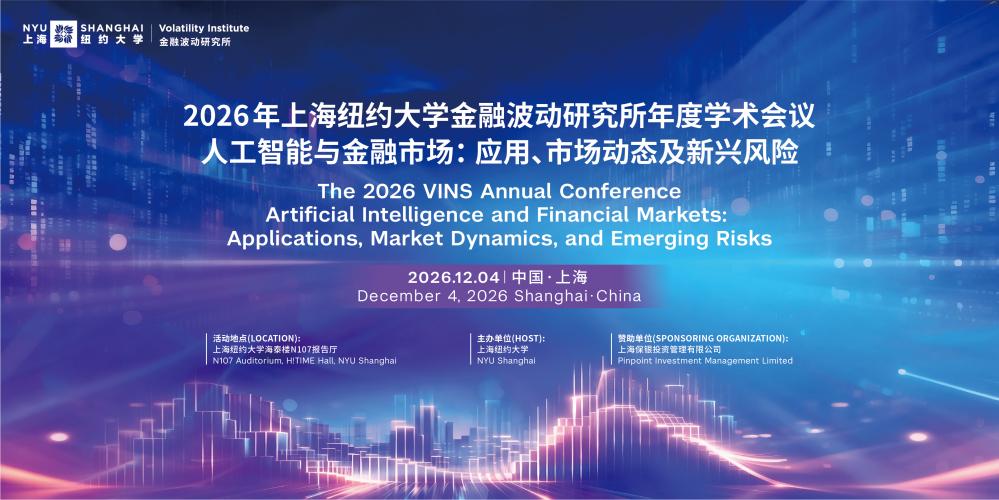
The 2026 Annual Volatility Institute Conference at NYU Shanghai
“Artificial Intelligence and Financial Markets: Applications, Market Dynamics, and Emerging Risks”
December 4, 2026
Shanghai, China
ORGANIZERS:
Volatility Institute at NYU Shanghai
CONFERENCE THEME
The Volatility Institute at NYU Shanghai (VINS) invites submissions of academic papers and policy proposals for its 2026 Annual Conference. This year’s conference focuses on the transformative impact of Artificial Intelligence, particularly Large Language Models (LLMs), on financial systems, alongside the novel operational, governance, and market risks stemming from widespread AI deployment.
Conference Highlights
- Keynote Address I: Professor Robert Engle (2003 Nobel Laureate in Economics)
- Keynote Address II: Professor Bryan Kelly (Frederick Frank ’54 and Mary C. Tanner Professor of Finance at the Yale School of Management)
- Keynote Address III: Professor Lin William Cong (President’s Chair Professor at Nanyang Technological University)
- Policy & Industry Roundtable: A high-level panel featuring financial regulators, industry leaders, and academic pioneers bridging theory, practice, and risk management.
Conference Agenda:
08:15–08:45 Registration
08:45–09:00 Opening Remarks
-Tong Shijun (Chancellor of NYU Shanghai)
-Jeffrey S. Lehman (Vice Chancellor of NYU Shanghai)
-Wu Bei (Provost of NYU Shanghai)
Session I: Chair-Zhou Xin (Co-Director, Volatility Institute at NYU Shanghai )
09:00–09:40 Keynote Address :TBD
Lin William Cong (President’s Chair Professor of Finance, Computing and Data Science; Associate Dean, Nanyang Technological University)
09:40–10:20 Keynote Address *:TBD
Bryan Kelly(Professor of Finance, Yale School of Management)
10:20–10:30 Coffee Break
10:30–11:00 Paper Presentation I: Does Your AI Move Your Money? Adoption and Impact of a Generative AI Investment Assistant
Zhang Xiaoyan (Tsinghua University)
11:00–11:30 Paper Presentation II: Visual Recovery
Wu Di (City University of Hong Kong)
11:30–12:00 Paper Presentation III: Agentic AI in Banking: Evidence from a Risk Management AI System
Wu Yuezhi (Fudan University)
12:00—13:30 Lunch
Luncheon Keynote : TBD
Richard Berner (Co-Director, Volatility and Risk Institute; Clinical Professor Emeritus of Finance and Professor of Management Practice, NYU Stern School of Business)
* Online Presentation
Session II: Chair Geoffery Zheng (Assistant Professor of Finance, NYU Shanghai)
13:30—14:00 Paper Presentation IV: Debiasing LLMs by Fine-tuning
Yan Yutong (The Chinese University of Hong Kong)
14:00—14:30 Paper Presentation V: Can AI Agents Learn to Misbehave? Strategic Exploitation and Financial Stability
Kumushoy Abduraimova (Durham University)
14:30—15:00 Paper Presentation VI: Beyond Alpha: Artificial Intelligence and Hedge Fund Risk
Qu Tianyi (Baylor University)
15:00—15:30 Paper Presentation VII (Online): Circular Investment in AI Compute Markets
Kumar Rishabh ( AI & the Digital Economy Lab, HEC Lausanne, University of Lausanne; Faculty of Business and Economics, University of Basel )
15:30—15:50 Coffee Break
15:50—16:40 Panel Discussion: AI and Financial Markets
Panelists:
Fei Binjie, Founder & CEO, ValueSimplex
Cindy Xin Zhou, Chairman, XY Investments LLC
Henry Zhang, Chief Scientist, Former Managing Director, Harvest Fund Management, China
Moderator: Jasmine Xu, Former Goldman Sachs Executive & Corporate Board Member
16:40—17:30 Keynote Address: TBD
Robert Engle (2003 Nobel Laureate in Economics Sciences, Professor Emeritus of Finance, NYU Stern)
17:30–17:35 Closing Remarks
Zhou Xin (Co-Director, Volatility Institute of NYU Shanghai)
* Conference agenda is subject to change.
Registration
We warmly welcome scholars, researchers, industry professionals, and anyone interested in the evolving intersection of artificial intelligence and financial markets to join us for a day of insightful keynote speeches, academic presentations, and engaging discussions.
Attendance is free of charge, but advance registration is required.
Please register through the link.
CONFERENCE SCIENTIFIC COMMITTEE
Professor Yakov Amihud, NYU Stern School of Business, New York City, United States
Clinical Professor Emeritus of Finance Richard Berner, NYU Stern School of Business, New York City, United States
Professor Emeritus of Finance Robert Engle, NYU Stern School of Business, New York City, United States
Professor Emeritus of Finance Stephen Figlewski, NYU Stern School of Business, New York City, United States
Professor Marti Subrahmanyam, NYU Stern School of Business, New York City, United States
Professor Qian Sun, Fudan University, Shanghai, China
Professor Jianye Wang, Volatility Institute of NYU Shanghai, Shanghai, China
Professor Robert Whitelaw, NYU Stern School of Business, New York City, United States
Professor Yexiao Xu, University of Texas at Dallas, Dallas, United States
Professor Hong Yan, Shanghai Advanced Institute of Finance at Shanghai Jiao Tong University, Shanghai, China
Professor Jianfeng Yu, Tsinghua SEM, Beijing, China
Professor Chu Zhang, Hong Kong University of Science and Technology, Hong Kong, China
Professor Harold Zhang, University of Texas at Dallas, Dallas, United States
Professor Zhenlong Zheng, Xiamen University, Xiamen, China
CONTACT INFORMATION
Website: Annual Conference | VINS | NYU Shanghai
Email: vins@nyu.edu
Telephone: +86 021 2059 5745
Address: S727, 567 West Yangsi Road, NYU Shanghai, Pudong, Shanghai, China, 200126